
What Is Salary Sacrifice? The Complete 2026 Guide, in Partnership with Green Car Guide
Why 2026 is the year salary sacrifice went mainstream
Ask most people in the UK what salary sacrifice is and you will hear "something to do with pensions". That is still true, but in 2026 the phrase has come to mean something else as well: the cheapest way for most employees to drive a brand-new electric car. The BVRLA's January 2026 Leasing Outlook recorded a 123% year-on-year rise in the salary sacrifice fleet, the fastest growth anywhere in the leasing market, and battery electric cars took a record 29.8% of the UK new car market in August 2026.
Three things drove that. Benefit-in-Kind on pure EVs is 4% for 2026/27 and legislated year by year to 2029/30, so the tax position is known before anyone signs. Employer National Insurance rose to 15% in April 2025, which made the employer's saving on every scheme bigger. And the cars themselves got cheaper: a Renault 5, a Ford Puma Gen-E or an MG4 now sit at price points where the monthly saving is worth having even for a basic-rate taxpayer.
This guide is a partnership between Green Car Guide and The Electric Car Scheme. Green Car Guide has been reviewing low-emission cars since 2006 and knows which EVs are worth your money. The Electric Car Scheme is Green Car Guide's exclusive salary sacrifice partner, and knows the tax mechanics that decide what those cars cost you each month. Between us, the aim is a single page that explains what salary sacrifice is, how it works on an electric car, what it saves, where the small print bites, and what you and your employer each have to do to get one on the drive. If you are a Green Car Guide reader who already knows which car you want, the numbers are in the worked examples below and the Green Car Guide savings calculator will run them on your own salary.
What is salary sacrifice?
Salary sacrifice is an agreement between you and your employer to give up part of your gross salary in exchange for a non-cash benefit of the same value. Because the benefit comes out of your pay before Income Tax and National Insurance are calculated, you pay both on a smaller salary. The one-line version is that you pay for the benefit before tax rather than after it.
The distinction that matters is gross versus net. Your gross salary is what your contract says you earn. Your net salary is what lands in your bank account after Income Tax and employee National Insurance have been deducted. Anything you buy from net pay has already been taxed at your marginal rate, which for a higher-rate taxpayer means 42p in every pound has gone before you spend it. A salary sacrifice scheme moves the purchase to the gross side of that line, so the tax is never charged in the first place.
HMRC has recognised the mechanism for decades and sets out the conditions in its Employment Income Manual at EIM42750. The change has to be a genuine, written variation to your employment contract, it has to apply to future pay rather than pay you have already earned, and you cannot swap the benefit back to cash whenever you like. Where an employer gets this wrong, HMRC can deny the tax advantage and recover the tax and National Insurance that would otherwise have been due.
What can you salary sacrifice?
Cars are the fastest-growing use but not the oldest. Pension contributions are the most common salary sacrifice scheme in the UK, and the most generous, because the sacrificed salary goes into a registered pension with no Income Tax or National Insurance at all. The cycle-to-work scheme works on the same basis for bikes and safety equipment. Workplace nurseries, employer-provided technology and, less commonly, additional holiday or gym membership can all run through salary sacrifice, though not all of them carry a tax advantage; some are taxed in full as a benefit in kind and the saving comes mainly from the employer's National Insurance. Our guide to salary sacrifice for pensions covers the pension side. The rest of this article is about electric cars, because that is where the 2026 growth is and where Green Car Guide readers are asking the most questions.
How does EV salary sacrifice work?
An electric car salary sacrifice scheme is a lease, held by your employer, that you pay for out of your gross salary. Six steps take you from browsing to driving.
You pick the car. Any new or used electric car on the UK market is eligible through The Electric Car Scheme, our round-up of the best electric cars to salary sacrifice is a sensible shortlist, and the best EV deals page shows what is competitively priced this month. You choose the term (24, 36 or 48 months for a new car) and an annual mileage between 5,000 and 30,000.
Your employer signs. If your company already runs a scheme, this step has happened. If not, it signs a scheme agreement with the provider and a lease agreement for your car. There is no set-up fee with The Electric Car Scheme and no cost to the employer for running it.
The deduction comes off your gross pay. Your employer reduces your gross salary by the monthly lease cost and pays the lease. Income Tax and National Insurance are then calculated on the lower figure. This is the step that produces the saving.
Benefit-in-Kind is applied. Because you have the private use of a company car, HMRC charges tax on a small percentage of its list price. For a pure EV in 2026/27 that percentage is 4% of the P11D value, and you pay Income Tax on that amount at your marginal rate. On a £27,000 car that is a taxable benefit of £1,080 a year, or £18 a month for a basic-rate taxpayer. A petrol equivalent would sit at around 29%.
The lease runs. Servicing, maintenance, tyres, MOT and breakdown cover are bundled into the monthly figure, and fully comprehensive insurance and a home charger can be added. You drive the car.
The term ends. You hand the car back and either take another one or leave the scheme. There is no balloon payment and you do not own the car, which is what keeps the monthly cost down. The salary sacrifice car lease explained page walks through the end-of-term options in more detail.
Worked example: Renault 5 E-Tech at £35,000 and £60,000
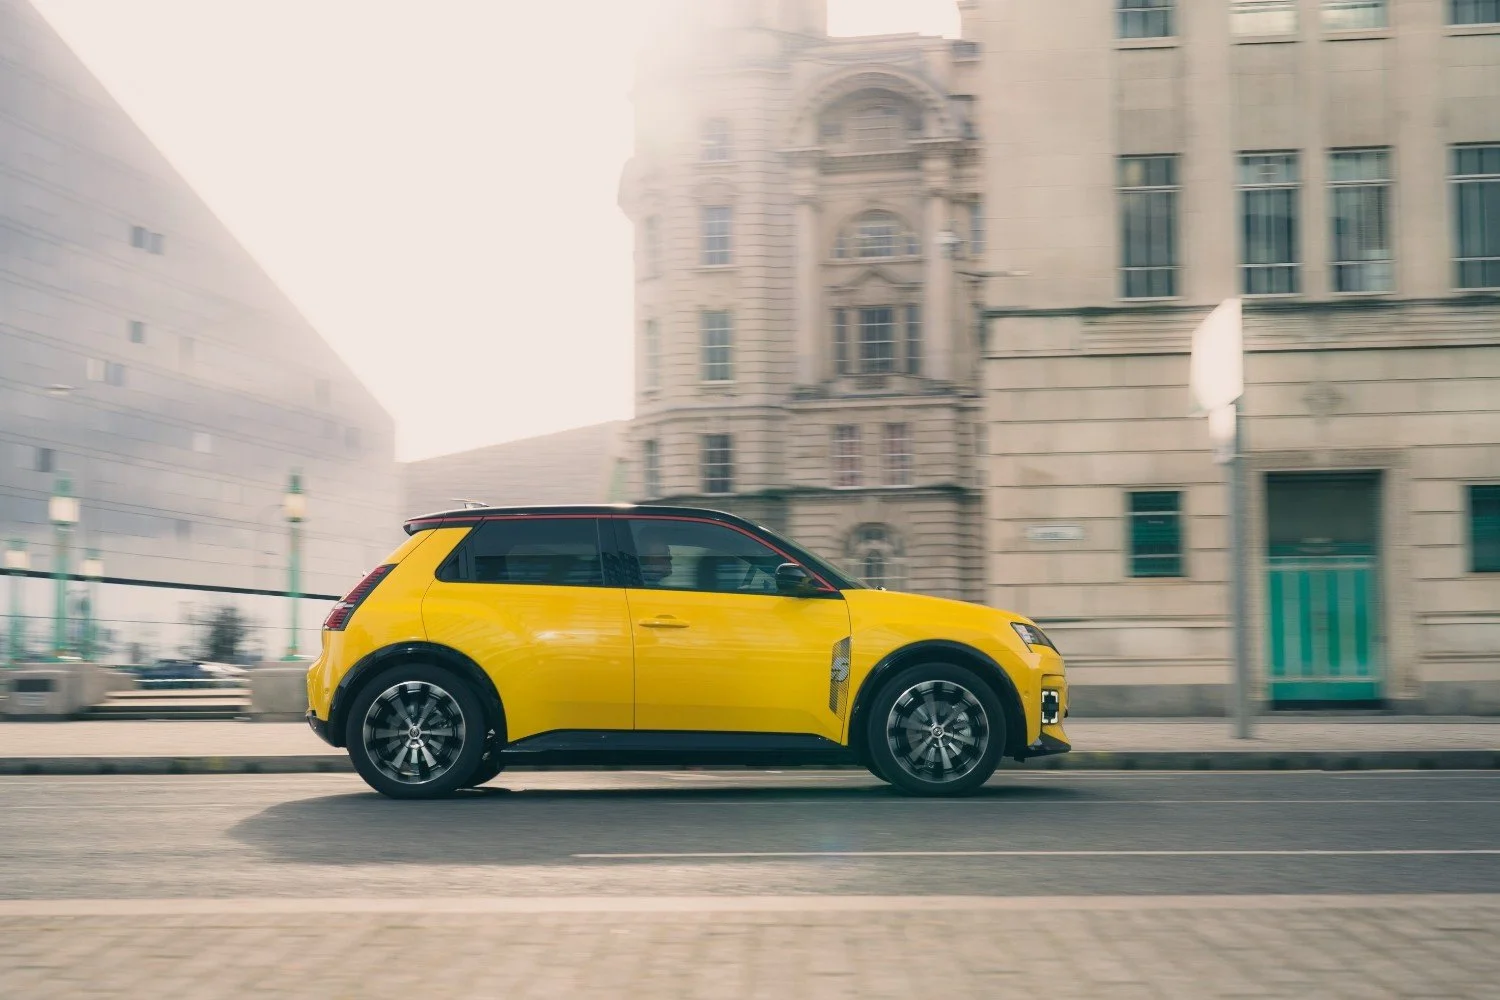
The Renault 5 E-Tech is the car Green Car Guide readers ask us about most often, so it is the one we have used here. The figures below use the 110kW Techno + Comfort Range 52kWh (252 miles WLTP), on a 48-month lease at 10,000 miles a year with maintenance included and insurance excluded. The gross monthly cost of £387.50 was taken from The Electric Car Scheme's calculator on 16 September 2026; the tax lines use HMRC's published 2026/27 rates and a P11D value of approximately £27,120. All figures are illustrative and your own quote will differ with your car, term, mileage and salary.
| Employee on £35,000 | Employee on £60,000 | |
|---|---|---|
| Gross monthly sacrifice | £387.50 | £387.50 |
| Income Tax saved (20% / 40%) | £77.50 | £155.00 |
| Employee NI saved (8% / 2%) | £31.00 | £7.75 |
| Benefit-in-Kind tax on 4% of £27,120 | +£18.08 | +£36.16 |
| Net monthly cost | approx. £297 | approx. £261 |
| Monthly saving vs paying from net pay | approx. £90 (23%) | approx. £127 (33%) |
| Saving over 48 months | approx. £4,340 | approx. £6,080 |
Two things stand out. The higher earner saves more in cash terms because their marginal Income Tax rate is double, even though their National Insurance saving is smaller. And the Benefit-in-Kind charge, the line that puts people off, is £18 to £36 a month. On a petrol car at 29% BiK the same line would be £131 to £262. The employee tax savings guide shows the same arithmetic across the full range of tax bands, and our nine real salary sacrifice examples run it on other cars.
For the employer, the same £4,650 a year of sacrificed salary saves around £697 in Class 1 National Insurance at 15%, less a Class 1A charge of roughly £163 on the car's taxable benefit, a net saving in the region of £535 per employee per year with nothing paid to set the scheme up.
What are the benefits for employees?
The saving is the headline, and it is real: 20-50% off the cost of the car depending on your tax band, with basic-rate taxpayers at the bottom of that range and additional-rate taxpayers on more than £125,140 at the top. Any provider quoting more than 50% has folded the employer's National Insurance saving into the employee's number, and it is worth asking them to show the split.
The saving is not the only reason people sign up. You get a brand-new electric car, or a nearly-new one through used EV salary sacrifice with delivery inside 14 days, with no deposit. Everything sits in one monthly figure: servicing, maintenance, tyres, MOT, breakdown cover and, if you want them, fully comprehensive insurance and a home charger installation. Because the lease is in your employer's name, the credit decision is made on the company rather than on you personally, which matters if you are early in your career or have a thin credit file. And through The Charge Scheme you can put home, workplace and public charging through salary sacrifice as well, saving the same 20-50% on the electricity.
What if I leave my job?
This is the question that stops most people, and it is the right one to ask. Your employer holds the lease, so if you leave, the car has to be returned or the lease settled. How much that costs depends entirely on the provider's protection. With The Electric Car Scheme, Complete Employer Protection covers resignation, redundancy, dismissal, parental leave, long-term sickness, loss of licence and death from day one, with no exclusion period, no excess and no usage caps. Anyone who resigns in their first three months pays no more than three months of deductions. Many other providers run a three-month exclusion period during which early termination is not covered at all, so read that clause before you compare monthly prices. Our guide to early termination liability sets out the scenarios in detail.
Does it affect my pension, mortgage or maternity pay?
It can, and you should check before you sign. Because your gross salary falls, anything calculated from it can fall too. Employer pension contributions based on a percentage of salary will reduce unless your employer calculates them on your pre-sacrifice pay, which many do and which you can ask for. Statutory Maternity, Paternity and Sick Pay are worked out from average earnings after the sacrifice. Some mortgage lenders assess affordability on gross post-sacrifice salary while others add the benefit back, so if you are about to apply, ask the lender and ask your employer for a letter confirming your reference salary. The is salary sacrifice worth it guide weighs these effects against the saving for different situations.
Is there a minimum salary?
Yes. Your pay after the sacrifice cannot fall below the National Minimum Wage, which is £12.71 an hour for those aged 21 and over from April 2026, or about £24,785 a year on a 37.5-hour week. An employee on £35,000 sacrificing £4,650 a year for the Renault 5 above lands at £30,350, comfortably clear. Providers check this at quote stage, and it is the most common reason lower earners are steered towards a cheaper car or a shorter term.
What does an employee actually have to do?
Less than you would think. For most employees the whole process takes about 20 minutes of active effort, spread over a few weeks while the car is built or sourced.
Check your eligibility. You need to be a permanent employee on PAYE, past probation, and earning enough to stay above the National Minimum Wage after the deduction. With The Electric Car Scheme, six months' tenure is the usual threshold.
Calculate your saving. Put your salary and a shortlist of cars into the salary sacrifice calculator. It shows gross cost, net cost and the saving side by side.
Check whether your employer already offers a scheme. If yes, skip to step 5. If not, send them the employer pack: the Convince Your Company toolkit contains an employee interest template, a business case template and a one-page summary of the 2026/27 tax position. Most HR teams have never been asked and are more receptive than employees expect.
Wait for your employer to sign up. This is the part that is out of your hands, and the next section explains what it involves for them. With a responsive employer it is a matter of days.
Choose your car and get a formal quote. Set the term, mileage, insurance and charger options and get the final monthly figure for your salary.
Sign the agreement. This is the contract variation that makes the salary sacrifice scheme valid, plus the driver agreement for the car. It is done electronically.
Take delivery. New cars typically arrive in 8-16 weeks; used cars in 2-4 weeks. The salary deduction starts from delivery, not from signing.
What does HR, finance or payroll have to do?
This section is written for the person the employee forwards this article to, and it is deliberately honest. Running a salary sacrifice car scheme does involve payroll and tax administration. The point of a specialist provider is that almost all of it is done for you.
Sign-up and contract. The employer signs a scheme agreement with the provider and, for each car, a business lease agreement. The employer is the lessee. With The Electric Car Scheme there is no set-up fee and no ongoing charge to the business; the provider is paid out of the lease. The how it works for companies page sets out the agreement in full.
Contract variation. Each participating employee signs a variation to their employment contract reducing their gross salary by the lease amount. HMRC's employer guidance requires this to be in writing and prospective. The provider supplies the template.
Payroll deduction set-up. Payroll reduces the employee's gross pay by the monthly amount before PAYE is calculated and reports the reduced figure on the Full Payment Submission (FPS) as normal. Nothing changes on the Employer Payment Summary (EPS) unless you are recovering statutory payments. This is a one-line change per employee in any mainstream payroll system, and the provider sends a monthly schedule of deductions so payroll is not calculating anything.
Benefit-in-Kind reporting. The car is a taxable benefit, so the employer reports it and pays Class 1A National Insurance on the taxable value. For 2026/27 that is done on form P11D and P11D(b) after the tax year ends, or by payrolling the benefit in-year if the employer is registered to do so. From 6 April 2027 payrolling becomes mandatory for company cars, so employers starting a scheme now will want to set up payrolling from the outset rather than switch later. The provider supplies the P11D values, the CO2 figures (zero) and the BiK calculations.
Early termination. If an employee leaves, the employer is the party liable to the funder for the remaining lease. This is the single biggest reason finance teams say no, and it is the reason the protection wording matters more than the monthly price. Complete Employer Protection from The Electric Car Scheme covers resignation, redundancy, dismissal, parental leave, long-term sickness, loss of licence and death with no exclusion period and no excess, so the employer's exposure is removed rather than reduced.
Communications launch. The scheme only saves money if employees use it. The provider runs the launch: a webinar, a benefits-portal listing, email copy and a dedicated employee support line. Organisations that run a short internal poll first tend to see response rates above 50%, which is also the evidence the finance director wants before approving.
How do I pitch this to my employer?
If you are the employee doing the forwarding, the argument that lands is not "I would like a cheaper car". It is that the scheme costs the business nothing, saves it around 15% in National Insurance on every pound sacrificed, and is a benefit 48% of UK employees told Fleet News they would like access to. Our 2026 survey of more than 250 senior HR professionals found that 86% planned to offer an EV salary sacrifice scheme in the coming year but 79% still believed it would cost the business money to launch. Correcting that one belief is usually all the pitch requires, and the employer explainer does it in two pages.
What are the benefits for employers?
Cost is the first one, because it is the objection. There is no set-up fee and no running cost. The employer's National Insurance saving on each car is 15% of the sacrificed salary less Class 1A on the benefit, which on the Renault 5 above is roughly £535 a year and on a £700-a-month car is closer to £1,000. Across 20 cars that is a five-figure sum a year, and the employer can choose to keep it, pass it back to employees to lower their monthly cost, or put it towards other benefits.
Recruitment and retention follow. A car scheme is a tangible, visible benefit that compares well against a salary rise of the same cost to the business, because the employee's saving is tax-funded rather than employer-funded. It is also one of the few benefits that reaches employees across every band, from a £134-a-month Dacia Spring to a £900-a-month Audi Q6 e-tron. Holland & Barrett, Leeds Bradford Airport, Millwall FC, TopCashback and Time Out Group PLC all run The Electric Car Scheme as a standard benefit.
Sustainability reporting is the third. Every employee who moves from a petrol car to an EV through the scheme is a measurable reduction in Scope 3 commuting emissions, and the provider supplies the data in a form that drops into an ESG report. For organisations with net zero commitments, the emissions case for salary sacrifice is often the argument that moves it from HR's agenda to the board's.
Why Green Car Guide chose The Electric Car Scheme
Green Car Guide has spent two decades test driving low emission cars, and its founder Paul Clarke has reviewed every electric car sold in the UK in that time, and telling readers which ones are worth having. When it came to recommending a way to pay for them, the same standard applied. Salary sacrifice providers look alike on a price comparison and differ enormously in what happens when something goes wrong, and it is the second part that decides whether an employee is glad they signed.
Paul Clarke - Founder & Editor, Green Car Guide.
The Electric Car Scheme was chosen as Green Car Guide's exclusive salary sacrifice partner on four counts.
Protection: Complete Employer Protection from day one with no exclusion period, no excess and no caps, plus Employee Life Event Support covering partner redundancy, a 20% or greater involuntary pay cut, divorce and overseas transfer.
Price: a multi-funder pricing engine that quotes across several UK leasing partners rather than a single funder, so the EV salary sacrifice comparison is done before the quote is issued.
Choice: any new or used EV on the market, with used cars delivered inside 14 days.
Service: a 4.9 out of 5 Trustpilot rating from verified customers, Best Salary Sacrifice Provider from Car Sloth in 2024 and 2025, and EV Salary Sacrifice Provider of the Year 2026 from SME News.
“Here at Green Car Guide our mission is to excite motorists to make the transition to electric cars. We do the reviews and the photography, but we wanted a partner that can deliver the cars that we review at the most affordable prices possible. The Electric Car Scheme is one of the most trusted companies to do this.” Paul Clarke, Founder & Editor, Green Car Guide.
Green Car Guide readers get the same scheme as everyone else. The Green Car Guide page on The Electric Car Scheme exists so the partnerships team can see which readers came from where, and so you can get a quote with your salary already in the calculator.
Frequently asked questions
What is salary sacrifice in simple terms?
Salary sacrifice is when you agree with your employer to take a benefit, such as a car or pension contribution, instead of part of your salary. Because the benefit is taken from your pay before tax, you do not pay Income Tax or National Insurance on that portion. The result is that the benefit costs you less than buying it from your take-home pay.
How does salary sacrifice work for an electric car?
Your employer leases the car and reduces your gross salary by the monthly lease cost. You pay Income Tax and National Insurance on the lower salary, and a Benefit-in-Kind charge of 4% of the car's list price for 2026/27. For most employees the net cost is 20-50% below leasing the same car privately, with servicing, maintenance, tyres and breakdown cover included.
Is salary sacrifice worth it for a basic-rate taxpayer?
Typically yes, though the saving is smaller than for a higher-rate taxpayer. A basic-rate employee saves 20% Income Tax plus 8% National Insurance on the sacrificed salary, and pays 20% on the 4% Benefit-in-Kind charge. On a Renault 5 E-Tech at £387.50 a month gross, that comes to a saving of around £90 a month, or roughly 23%.
Does salary sacrifice affect my pension?
It can. If your employer's pension contribution is a percentage of your salary, it will be calculated on the reduced figure unless your employer agrees to use your pre-sacrifice salary as the reference. Many employers do this, so ask before you sign. Your own contributions are unaffected if they are a fixed amount.
What happens if I leave my job during the lease?
The lease is your employer's, so the car is returned or the lease settled. Who pays depends on the provider's protection. With The Electric Car Scheme, resignation, redundancy, dismissal, parental leave, long-term sickness, loss of licence and death are all covered from day one with no exclusion period, and anyone resigning in their first three months pays no more than three months of deductions.
Can my employer refuse to offer salary sacrifice?
Yes. Salary sacrifice is a voluntary benefit and employers are not obliged to offer it. In practice most refusals come from a belief that it costs the business money, which for a scheme with no set-up fee is not the case. The Convince Your Company toolkit is designed to answer the questions HR and finance will ask.
Is there a minimum salary for salary sacrifice?
Your salary after the deduction must stay above the National Minimum Wage, which is £12.71 an hour for those aged 21 and over from April 2026, roughly £24,785 a year full time. There is no other statutory minimum, though providers set their own eligibility rules, and higher earners generally save more because their marginal tax rate is higher.
How much does salary sacrifice cost the employer?
With The Electric Car Scheme, nothing. There is no set-up fee and no running cost, and the employer saves 15% Class 1 National Insurance on every pound of salary sacrificed, less a small Class 1A charge on the car's taxable benefit. The net saving is typically £500 to £1,000 per car per year.
Next steps
If you are an employee, the fastest route to a real number is the calculator. See available cars and calculate your savings on your own salary, or start with the salary sacrifice cars page if you want to understand the scheme before you pick a car. If your employer does not yet offer a scheme, send them this article and the toolkit.
If you are in HR, finance or payroll and an employee has just sent you this page, book a demo and we will walk through set-up, payroll and protection for your organisation in 30 minutes. There is no cost to look and none to launch.
Last updated: 23.09.2026
Our pricing is based on data collected from The Electric Car Scheme quote tool. All final pricing is inclusive of VAT. All prices above are based on the following lease terms; 10,000 miles pa, 36 months, and are inclusive of Maintenance and Breakdown Cover. The Electric Car Scheme's terms and conditions apply. All deals are subject to credit approval and availability. All deals are subject to excess mileage and damage charges. Prices are calculated based on the following tax saving assumptions; England & Wales, 40% tax rate. The above prices were calculated using a flat payment profile. The Electric Car Scheme Limited provides services for the administration of your salary sacrifice employee benefits. The Electric Car Scheme Holdings Limited is a member of the BVRLA (10608), is authorised and regulated by the FCA under FRN 968270, is an Appointed Representative of Marshall Management Services Ltd under FRN 667174, and is a credit broker and not a lender or insurance provider.
Copyright and Image Usage: All images used on this website are either licensed for commercial use or used with express permission from the copyright holders, in compliance with UK and EU copyright law. We are committed to respecting intellectual property rights and maintaining full compliance with applicable regulations. If you have any questions or concerns regarding image usage or copyright matters, please contact us at marketing@electriccarscheme.com and we will address them promptly.
